
For centuries, gold has held a unique appeal as a store of value and a hedge against economic uncertainty. As of 2026, with global economic narratives continuing to evolve, many investors are re-evaluating gold’s role in their portfolios. A fundamental question often arises: Is it better to hold physical gold directly, or to invest through a Gold Exchange Traded Fund (ETF)? This article aims to compare these two distinct approaches, examining their advantages and disadvantages to help investors understand which option might align better with their financial goals.
Understanding Physical Gold Investments
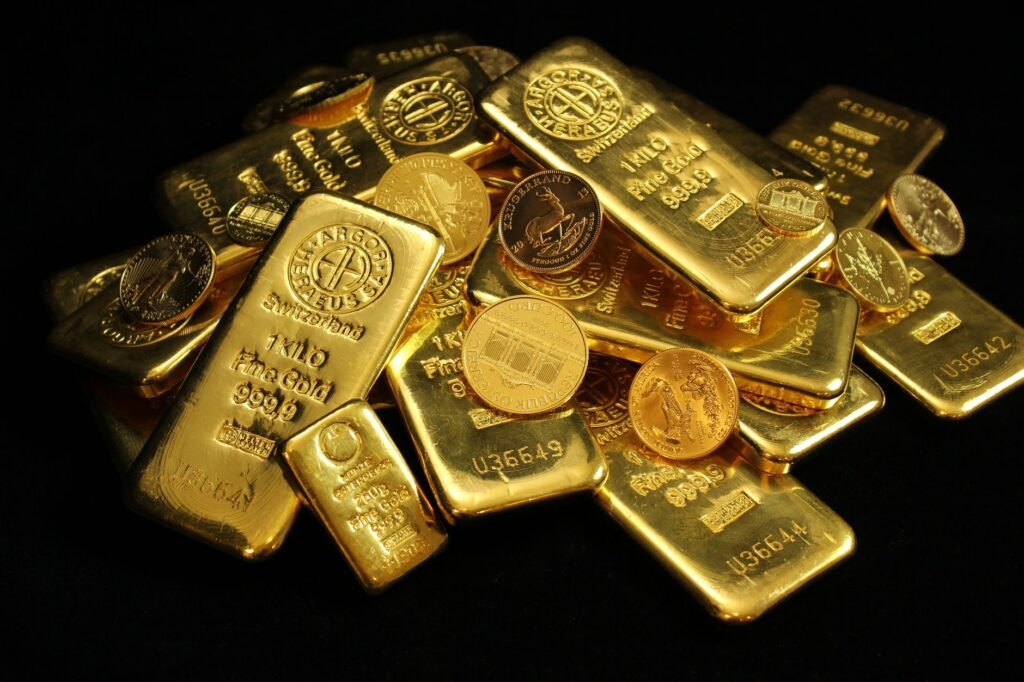
Investing in physical gold involves direct ownership of the precious metal itself. This typically comes in the form of gold bullion – bars, rounds, or ingots – or investment-grade gold coins. While some investors may consider numismatic coins for their collector’s value, the focus for pure investment purposes is generally on their intrinsic gold content.
Advantages of Physical Gold
- Tangible Asset: Many investors find psychological comfort in holding a tangible asset. In scenarios of extreme financial or geopolitical instability, direct ownership means no reliance on a financial institution or digital system.
- No Counterparty Risk: Once acquired, physical gold does not carry the counterparty risk associated with financial instruments. There’s no intermediary that could default or go bankrupt, assuming secure storage.
- Potential for Premium: While the primary value is based on the gold content, certain widely recognized investment-grade coins or smaller bullion products can sometimes command a slight premium over their melt value due to demand and collector interest.
- Privacy: Depending on the jurisdiction and transaction size, physical gold transactions can offer a degree of privacy that digital investments may not.
Disadvantages of Physical Gold
- Storage Costs and Security: Holding physical gold necessitates secure storage, whether in a home safe, a bank safe deposit box, or a specialized third-party vault. Each option incurs costs and inherent security risks.
- Insurance: To mitigate risks, physical gold holdings often require insurance, adding another layer of ongoing expense.
- Liquidity Challenges: Selling physical gold can be less immediate than trading an ETF. It often requires finding a reputable dealer, arranging for transport, and potentially undergoing authentication, which can incur delays and additional costs.
- Transaction Costs: Dealers typically sell physical gold at a premium over the spot market price and buy it back at a discount. These bid-ask spreads, along with potential assay fees, can impact overall returns.
- No Income Generation: Physical gold does not pay dividends or interest. Its return potential comes solely from price appreciation.
- Divisibility: Large gold bars are not easily divisible for smaller transactions or partial sales, making them less flexible than fractional ETF shares.
- Sales Taxes: In some regions, physical gold purchases may be subject to sales taxes, which can add a significant upfront cost.
In 2026, ongoing global geopolitical uncertainties and discussions around inflationary pressures continue to prompt some investors to consider the traditional safe-haven role of physical gold. The tangible nature of gold offers a form of assurance against potential disruptions to financial systems.
Exploring Gold Exchange-Traded Funds (ETFs)
Gold ETFs are investment funds that trade on stock exchanges, typically tracking the price of gold. The most common type of gold ETF is physically-backed, meaning the fund holds actual gold bullion in a vault to back the value of its shares. Other types may use futures contracts or other derivatives.
Advantages of Gold ETFs
- High Liquidity: Gold ETFs trade like stocks on major exchanges, offering high liquidity. Investors can buy and sell shares easily throughout the trading day at market prices.
- Lower Entry Barrier: Investors can purchase fractional shares, making it accessible to those with smaller amounts of capital or those wishing to invest incrementally.
- Cost-Effective Storage and Insurance: The fund handles storage and insurance, the costs of which are typically factored into a small annual expense ratio, often lower than the cumulative costs for individual physical gold holders.
- Diversification and Rebalancing: ETFs can be easily integrated into a diversified investment portfolio and rebalanced as needed with minimal transaction friction.
- Transparency: Most physically-backed gold ETFs provide regular reports on their gold holdings and vaulting arrangements, offering a degree of transparency to investors.
- Tax Efficiency (in some cases): Depending on the jurisdiction and specific ETF structure, some gold ETFs may offer tax advantages compared to direct physical ownership, particularly concerning capital gains or sales tax treatment.
Disadvantages of Gold ETFs
- No Direct Physical Ownership: While physically-backed, an ETF share represents a claim on a portion of gold, not direct ownership of a specific bar. This introduces counterparty risk with the fund issuer.
- Expense Ratios: ETFs charge an annual expense ratio, which, while small, can erode returns over long periods.
- Tracking Error: Occasionally, the price of an ETF may not perfectly track the spot price of gold due to various factors, including expense ratios, market inefficiencies, or specific fund structures.
- Brokerage Fees and Taxes: Investors typically incur brokerage commissions when buying or selling ETF shares, and capital gains taxes apply upon sale.
- Not a Tangible Asset in Hand: In an extreme scenario of systemic collapse, some investors may prefer the immediate tangibility of physical gold over an electronic claim.
In 2026, the digital investment landscape continues to make ETFs highly accessible through various brokerage platforms. The convenience and liquidity of gold ETFs continue to appeal to a broad spectrum of investors looking for exposure to gold without the logistical complexities of physical ownership.
Choosing the Right Path for 2026: Key Considerations
The decision between physical gold and gold ETFs ultimately depends on an individual investor’s goals, risk tolerance, and logistical preferences. Both options provide exposure to gold’s price movements, but they cater to different investor profiles.
Investment Goals and Horizon
If the primary goal is to hold gold as a long-term, tangible hedge against extreme economic disruption, or as an heirloom, physical gold might be the preferred choice. For investors seeking convenient, liquid exposure to gold’s price for portfolio diversification or tactical allocation, especially over shorter to medium horizons or with a view toward easy rebalancing, a gold ETF is often more suitable.
Risk Tolerance and Psychology
Investors deeply concerned about systemic financial collapse or currency debasement might find the no-counterparty-risk aspect of physical gold psychologically reassuring. Those comfortable with the structure of regulated financial markets and valuing ease of transaction and professional management may lean towards gold ETFs.
Capital and Logistics
For individuals looking to make smaller, regular investments into gold, or who lack the secure storage facilities for bullion, gold ETFs offer a significantly more practical solution. Conversely, investors with substantial capital who can arrange for high-security storage might consider physical gold for its direct ownership benefits.
Market Sentiment in 2026
As of 2026, global markets continue to grapple with persistent inflation concerns in various economies, central bank monetary policy shifts, and evolving geopolitical landscapes. Historically, these factors have often increased investor interest in gold as a perceived safe-haven asset. Financial commentators continue to debate the future trajectory of these macroeconomic forces, which influences the ongoing appeal of gold. Both physical gold and gold ETFs allow investors to participate in this market, but they do so through different practical and structural mechanisms.
Ultimately, the
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute financial, investment, trading, or legal advice. Gainsium is not a registered investment advisor. Markets are volatile and past performance does not guarantee future results. Readers should conduct their own research and consult a licensed financial advisor before making any investment decisions.