
As investors navigate the financial landscape of 2026, concerns about inflation often lead to seeking strategies to preserve purchasing power. Two prominent instruments frequently considered for hedging against inflation are gold and Treasury Inflation-Protected Securities (TIPS). Understanding the distinct characteristics of each can help investors determine which, if either, aligns with their portfolio objectives for managing inflation risk.
Understanding Inflation Hedges
Inflation, defined as the general increase in prices and fall in the purchasing value of money, can significantly erode the real returns of investments. An effective inflation hedge aims to maintain or increase an asset’s real value during periods of rising prices. Historically, various assets have been proposed as hedges, but gold and TIPS offer distinct mechanisms and investor experiences.
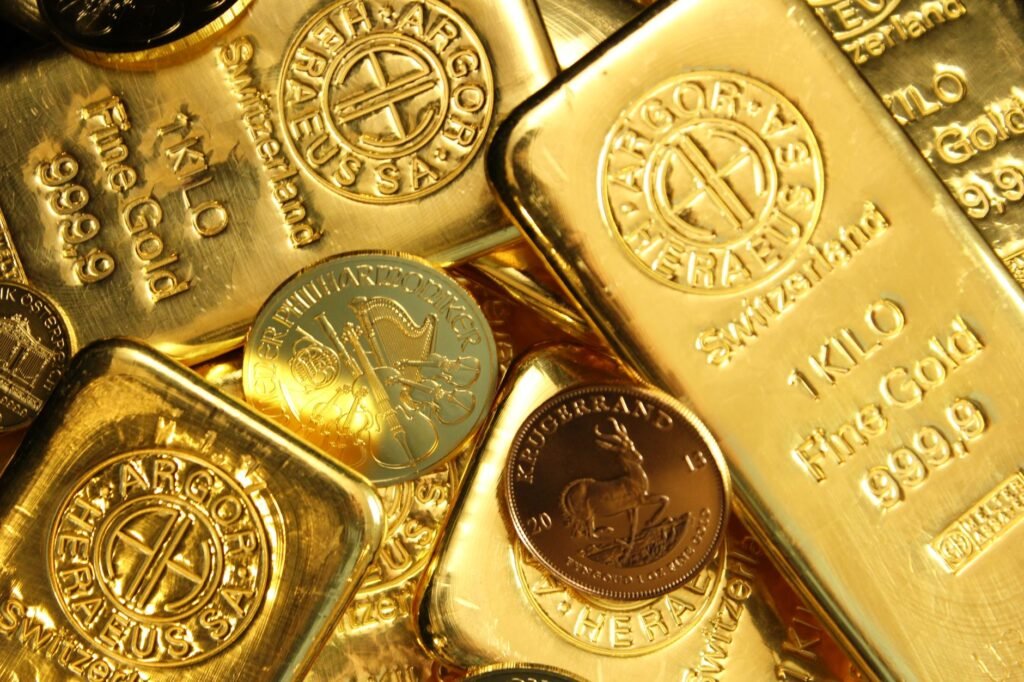
Gold as an Inflation Hedge
For centuries, gold has been revered as a store of value and a safe haven asset, particularly during times of economic uncertainty and currency devaluation. Its role in a portfolio often centers on its perceived ability to protect against inflation.
Characteristics of Gold
- Tangible Asset: Gold is a physical commodity, universally recognized and valued across cultures and economies.
- Store of Value: Many investors view gold as an intrinsic store of wealth, less susceptible to the policies of any single government or central bank.
- No Yield: Unlike bonds or dividend-paying stocks, physical gold does not generate income through interest or dividends.
- Price Volatility: The price of gold can be influenced by various factors beyond inflation, including supply and demand dynamics, geopolitical events, U.S. dollar strength, and broader investor sentiment.
Benefits of Gold
- Historical Performance: In some historical periods of high inflation, gold has demonstrated a tendency to preserve or increase its value, making it an attractive option when real interest rates are low or negative.
- Diversification: Gold’s correlation with traditional financial assets like stocks and bonds can sometimes be low, potentially offering diversification benefits within a portfolio.
- Global Liquidity: Gold is a highly liquid asset, tradable worldwide through various instruments, including physical bullion, futures contracts, and exchange-traded funds (ETFs).
Drawbacks of Gold
- No Income Generation: As a non-yielding asset, investors only profit from price appreciation, which can be unpredictable.
- Storage and Insurance Costs: Holding physical gold necessitates secure storage and potentially insurance, which incurs ongoing costs. Indirect exposure through gold ETFs or mining stocks carries its own set of risks, such as management fees or company-specific risks.
- Inconsistent Hedge: While often considered an inflation hedge, gold’s effectiveness can be inconsistent. Its price may not always track inflation directly, and other factors can dominate its movements. For example, in 2026, while inflation remains a consideration, interest rate policies, central bank activities, and geopolitical stability also heavily influence precious metal markets.
Treasury Inflation-Protected Securities (TIPS)
Treasury Inflation-Protected Securities (TIPS) are a different approach to inflation hedging, offered by the U.S. government. They are designed specifically to shield investors from the erosive effects of inflation.
Characteristics of TIPS
- Government-Issued Bonds: TIPS are U.S. Treasury bonds carrying the full faith and credit of the U.S. government, making them considered very low-risk in terms of default.
- Principal Adjustment: The principal value of a TIPS bond adjusts semi-annually based on changes in the Consumer Price Index (CPI), the official measure of inflation.
- Fixed Interest Rate: TIPS pay a fixed interest rate on their adjusted principal. As the principal increases with inflation, the dollar amount of the interest payments also rises.
- Deflation Protection: At maturity, investors receive either the inflation-adjusted principal or the original principal, whichever is greater, offering some protection against deflationary periods.
Benefits of TIPS
- Direct Inflation Protection: TIPS offer an explicit and direct hedge against inflation, as their principal and interest payments are contractually linked to the CPI. This makes them a precise tool for maintaining purchasing power.
- Capital Preservation: The inflation adjustment helps preserve the purchasing power of the invested capital over time.
- Regular Income: TIPS provide semi-annual interest payments, which can be beneficial for income-seeking investors, and these payments naturally increase with inflation.
- Low Default Risk: As obligations of the U.S. government, TIPS are considered among the safest investments in terms of credit risk.
Drawbacks of TIPS
- Taxation of
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute financial, investment, trading, or legal advice. Gainsium is not a registered investment advisor. Markets are volatile and past performance does not guarantee future results. Readers should conduct their own research and consult a licensed financial advisor before making any investment decisions.